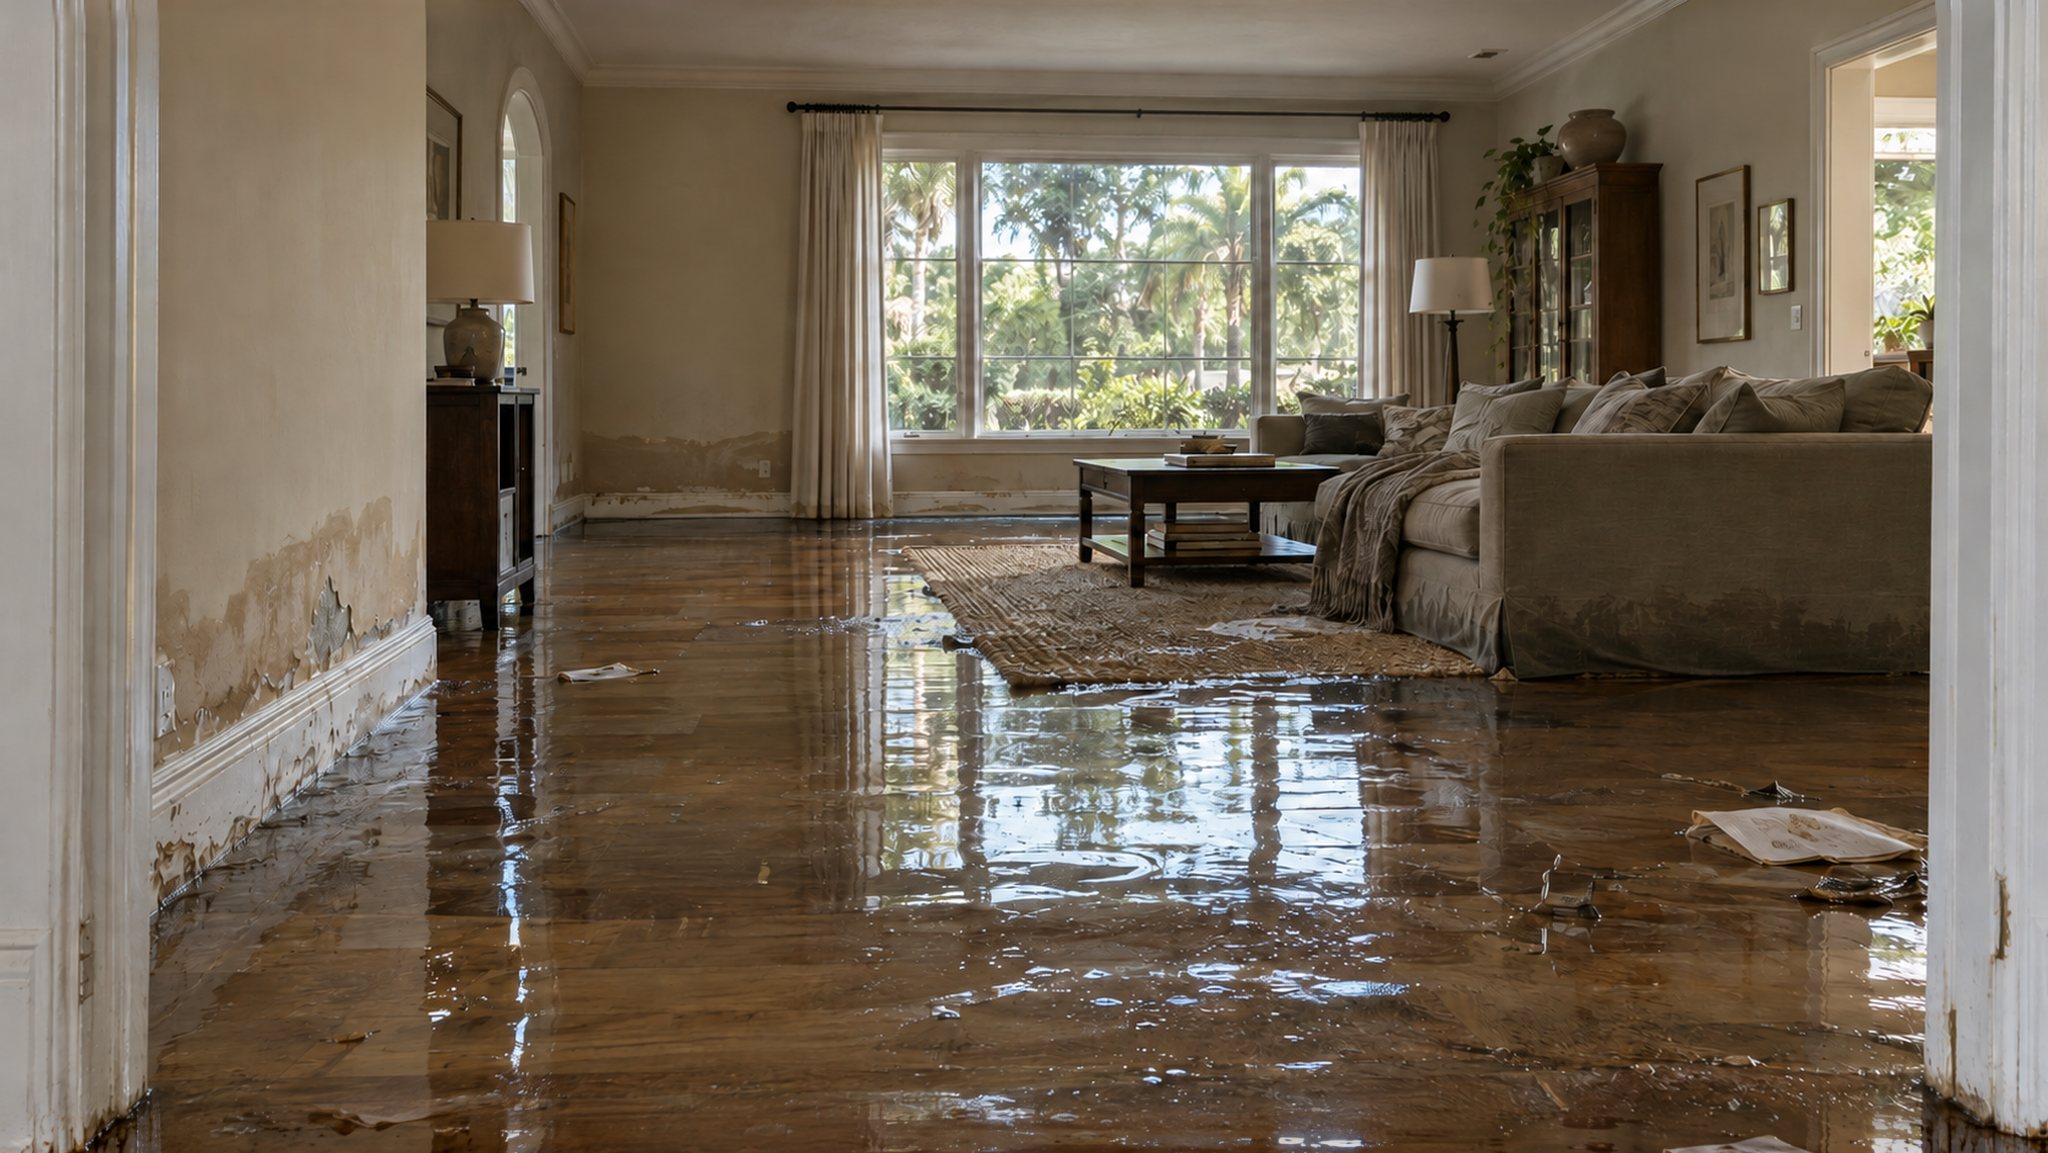
A living room with shallow floodwater on the wood floor and water stains on the walls
Let’s talk (305) 400-1035

YOUR PROPERTY. YOUR ADVOCATE.

When home
feels different.

You don’t have to face the claim alone.
Our public adjusters document the damage and guide you through what comes next.

From the first inspection to the final settlement.

WHAT WE DOCUMENT

The loss, point by point.

A public adjuster inspects, records and estimates the damage before it is presented to your insurance company.

0of 5 points documented

    THE FULL SCOPE

    Every room. Every trade.

    Wind and water rarely stop at what you can see from the doorway. We prepare a full estimate of the loss.

    1 yearto give your insurer notice of a new claim, counted from the date of loss. s. 627.70132, Florida Statutes

    WHAT SHOWS UP LATER

    Not all damage shows on day one.

    The room dries out and looks fine. Moisture left behind can surface weeks later.

    Week 1after the water is gone

    18 monthsto give notice of a supplemental claim, counted from the date of loss. Mold coverage depends on your policy. s. 627.70132, Florida Statutes

    WHAT IS MISSING COUNTS TOO

    Every item, accounted for.

    We build the contents list: what was taken, what was broken, and what it costs to replace.

    0of 4 items on the list

      THE GOAL

      Your home,
      as it was before.

      We work for you, not the insurance company, from the first inspection to the final settlement.

      Illustrative scenes. Every claim depends on its policy and its loss.

      WATER DAMAGE

      FILE 01 WHOSE SIDE

      Your insurer has an adjuster.
      You can have one too.

      The room you just scrolled through will be inspected by someone. The question is who that person works for.

      Question
      Your insurer’s adjusterStaff or independent. An “independent” adjuster is hired by the insurer, not independent of it.
      Your public adjusterLux Claims
      Who hires themThe insurance companyYou
      Whose estimate they writeThe insurance company’sYours
      Who they answer toThe insurance companyYou

      FILE 02 WHAT A QUICK LOOK MISSES

      It looks fine.
      Look again.

      Each photo hides several signs of the same loss. Look first, then switch to the adjuster’s view.

      A hall bathroom seen from the hallway: a dark-wood vanity, cream floor tile, a jute mat and the hallway's hardwood floor at the door. Everything looks normal at first glance.

        A slow leak from the shower pan in the hall bathroom.

        6

        things in this photo belong to the same leak.

        How many can you find before you switch views?

        ALSO NOT IN THE PHOTO

        • Opening the shower floor to reach the leaking pan, and rebuilding the shower.
        • Drying the room: fans, dehumidifiers and the moisture readings that show when it is dry.
        • Matching: when replacement tile, boards or cabinets will not match what is left, Florida law requires reasonable repair or replacement in the adjoining areas.

        Pinch to zoom, drag to look around.

          FILE 03 THE WORK

          The room showed four words.
          The claim needs six.

          Four of the six happen at your property, where you can see them. The other two, presented and negotiated, happen with your insurance company, out of sight.

          1. 01Inspected.

            We walk the property with you and review your policy. The first inspection and policy review are free.

          2. 02Documented.

            Photographs, measurements, moisture readings and a list of damaged or missing contents.

          3. 03Estimated.

            A line-by-line estimate of what it takes to return the property to its condition before the loss.

          4. 04Presented.

            The claim goes to your insurer, and we are there when their adjuster inspects the property.

          5. 05Negotiated.

            We review the insurer’s report and payment line by line and negotiate what is missing.

          6. 06Supplemented.

            If more damage surfaces later, we give notice of a supplemental claim within the deadline.

          MEANWHILE YOUR PART

          • Report the loss to your insurance company as soon as you can.
          • Prevent further damage where it is safe to, and keep every receipt.
          • Photograph before anything is thrown away, including what you remove from the room.

          FILE 04 DATES ON THE FILE

          The clock starts
          on the day of the loss.

          Enter the date of loss to see the last day to give your insurer notice of each kind of claim.

          New or reopened claim—1 year after the date of lossEnter a date of loss
          Supplemental claim—18 months after the date of lossEnter a date of loss

          s. 627.70132, Florida Statutes. For hurricanes and other weather events, the date of loss is the landfall date or the date NOAA verifies the event. Your policy may set its own terms. This is general information, not legal advice; confirm your dates with us.

          FILE 05 QUESTIONS

          Straight answers
          before you sign anything.

          The questions homeowners ask us first. If yours isn’t here, call (305) 400-1035.

          What does a public adjuster cost?

          Nothing up front. Our fee is a percentage of what your insurer pays, agreed in writing before we start. If the claim pays nothing, there is no fee.

          Florida caps the fee: 10% for claims from an event under a state of emergency declared by the Governor, during the year after the declaration; 20% for other claims; and 20% of a reopened or supplemental claim payment. No fee is due on anything your insurer paid, or agreed in writing to pay, before you signed with us. s. 626.854(11), Florida Statutes.
          Do I have to hire a public adjuster?

          No. You can present a claim yourself. A public adjuster is someone you can hire to inspect, document, estimate and negotiate the claim on your behalf.

          Will hiring a public adjuster upset my insurer or slow my claim?

          No. Insurers work with public adjusters every day, and you can hire one at any point in the claim. Once you sign, we handle the communication with your insurer and keep you informed at every step. A well-documented claim gives the insurer fewer reasons to come back with questions.

          How long does a claim take?

          It depends on the size of the loss and on how your insurer responds. Florida law sets deadlines for the insurer to respond and to pay or deny a claim. We track them on your file and follow up when they are missed.

          My insurer already paid or closed the claim. Is it too late?

          Not always. A closed claim can be reopened with notice within 1 year of the date of loss, and a supplemental claim for additional damage from the same event can be noticed within 18 months. Check your dates ↑

          s. 627.70132, Florida Statutes.
          Can I keep my own contractor?

          Yes. You choose who does the repairs. We work the claim, and we can share the documented scope with your contractor so their estimate and the claim describe the same damage.

          Do you handle business and commercial property?

          Yes, including business interruption and income loss after covered property damage. Tell us about the property in the form below.

          Contractor? See how we work together →

          FILE 06 OPEN A FILE

          Tell us what happened.
          We open the file.

          A free first conversation about your property, your policy and your dates.

          (305) 400-1035 claims@luxclaims.com

          Mon–Fri, 9:00 am–6:30 pm

          Helpful to have: your policy, the date of loss, photos of the damage and any letters from your insurer. Missing paperwork shouldn’t stop you from calling.

          NEW FILELX-—

          Your details go straight to our claims team. Prefer to talk? Call (305) 400-1035.

          Get a free consultation Talk to our team (305) 400-1035